Does Insurance Cover Roof Leaks in Florida?
What's covered, what isn't, the 1-year claim deadline, hurricane and roof deductibles, and how to file. Plain answers for Valrico homeowners.
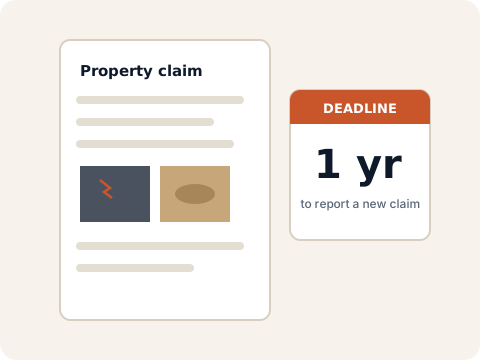
Does insurance cover roof leaks in Florida? Usually yes if the leak was caused by something sudden, like wind or a falling limb, and usually no if it comes from wear and tear or an old roof. Flood is excluded from standard policies. You have 1 year from the date of loss to report a new claim. This is general information, not legal advice; your policy and insurer have the final word. For the repair itself, see our roof leak repair in Valrico, FL.
What's usually covered, and what isn't
The honest answer to “does insurance cover roof leaks in Florida” depends on what caused the leak:
| Cause of the leak | Usually covered? |
|---|---|
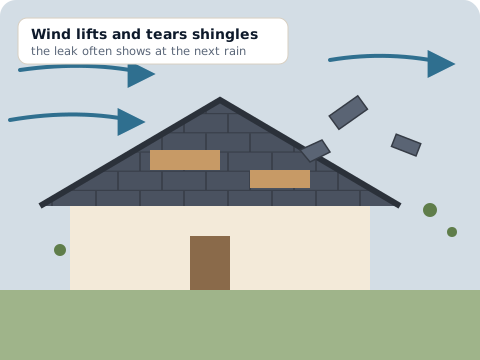
| Wind lifts or tears off shingles or tiles | Yes, minus your deductible |
| Tree limb or debris through the roof | Yes, minus your deductible |
| Hurricane damage | Yes, minus the hurricane deductible |
| Wear and tear, old age, worn underlayment | No |
| A leak ignored until it caused rot or mould | Often limited or denied |
| Rising water or storm surge (flood) | No, needs separate flood insurance |
The water damage inside, like ceilings, insulation and drywall, is often covered when the cause is covered. The roof repair itself may be treated differently if the roof was already worn.
Florida rules that affect roof claims
- Claim deadline. New or reopened claims must be reported within 1 year of the date of loss; supplemental claims within 18 months (Florida Senate SB 2-A analysis).
- Hurricane deductible. Usually 2%, 5% or 10% of dwelling coverage. If more than one hurricane hits in the same coverage year, the hurricane deductible is paid once and later damage falls under the regular deductible (Florida Senate guidance).
- Roof deductibles and actual cash value. Since 2022, insurers can offer a separate roof deductible and pay only actual cash value until you show you've paid it (summary of SB 2-D). The amount must be shown on your declarations page.
- Roof age. Under Florida Statute 627.7011, an insurer can't refuse or non-renew a policy only because the roof is under 15 years old. At 15 or older, an inspection showing 5 or more years of life left keeps it insurable.
- No assignment of benefits. For policies issued since January 1, 2023, you can't sign your benefits over to a contractor.
- No deductible waivers. A contractor offering to cover or waive your deductible is breaking Florida Statute 489.147.
How to file a roof leak claim, step by step
- Stop more damage.Catch the water, tarp the roof if needed, and keep receipts. Insurers expect this. See emergency roof tarping.
- Photograph everything.The roof from the ground, the ceiling, the attic, damaged belongings. Date and time help.
- Get a written repair estimate.An itemised price shows whether the claim is bigger than your deductible.
- Report the claim.Within 1 year. Write down your claim number and the adjuster's name.
- Meet the adjuster.Your roofer can be there to point out damage and share photos.
So, does insurance cover roof leaks in Florida for your house?
It depends on the cause, your deductibles and your roof's age. Start with a roof inspection and photos, then talk to your agent. If the storm was recent, see storm damage roof repair.
Roof insurance questions
Does homeowners insurance cover a leaking roof in Florida?
It covers sudden damage, like wind tearing off shingles or a limb going through the roof, and usually the water damage that follows. It doesn't cover wear and tear, an old roof that has simply aged out, or flood.
How long do I have to file a roof claim in Florida?
One year from the date of loss for a new or reopened claim, and 18 months for a supplemental claim. For hurricanes, the date of loss is the landfall date.
What is a hurricane deductible?
A separate deductible for named-storm damage, usually 2%, 5% or 10% of your dwelling coverage rather than a flat dollar amount. On a $350,000 dwelling limit, 2% is $7,000.
Can my insurer pay less because my roof is old?
Some policies now pay roof claims on a depreciated or actual cash value basis for older roofs, or have a separate roof deductible. Check your declarations page: Florida requires the roof deductible amount to be shown there.
Can a roofer handle my claim for me?
A roofer can document damage, give you photos and an itemised estimate, and meet the adjuster. Since 2023, you can't assign your policy benefits to a contractor, and nobody can legally waive your deductible.
Should I file a claim for a small leak?
If the repair costs less than your deductible, a claim won't pay anything and may still go on your record. Get a written repair price first, then decide.
Need photos and a written estimate for your claim?
Call (813) 555-0147 or text us a photo of the stain. We'll find where the water is getting in, show you, and give you a written price.